Most OFM agency owners learn this the hard way: traditional banks don't want the business.
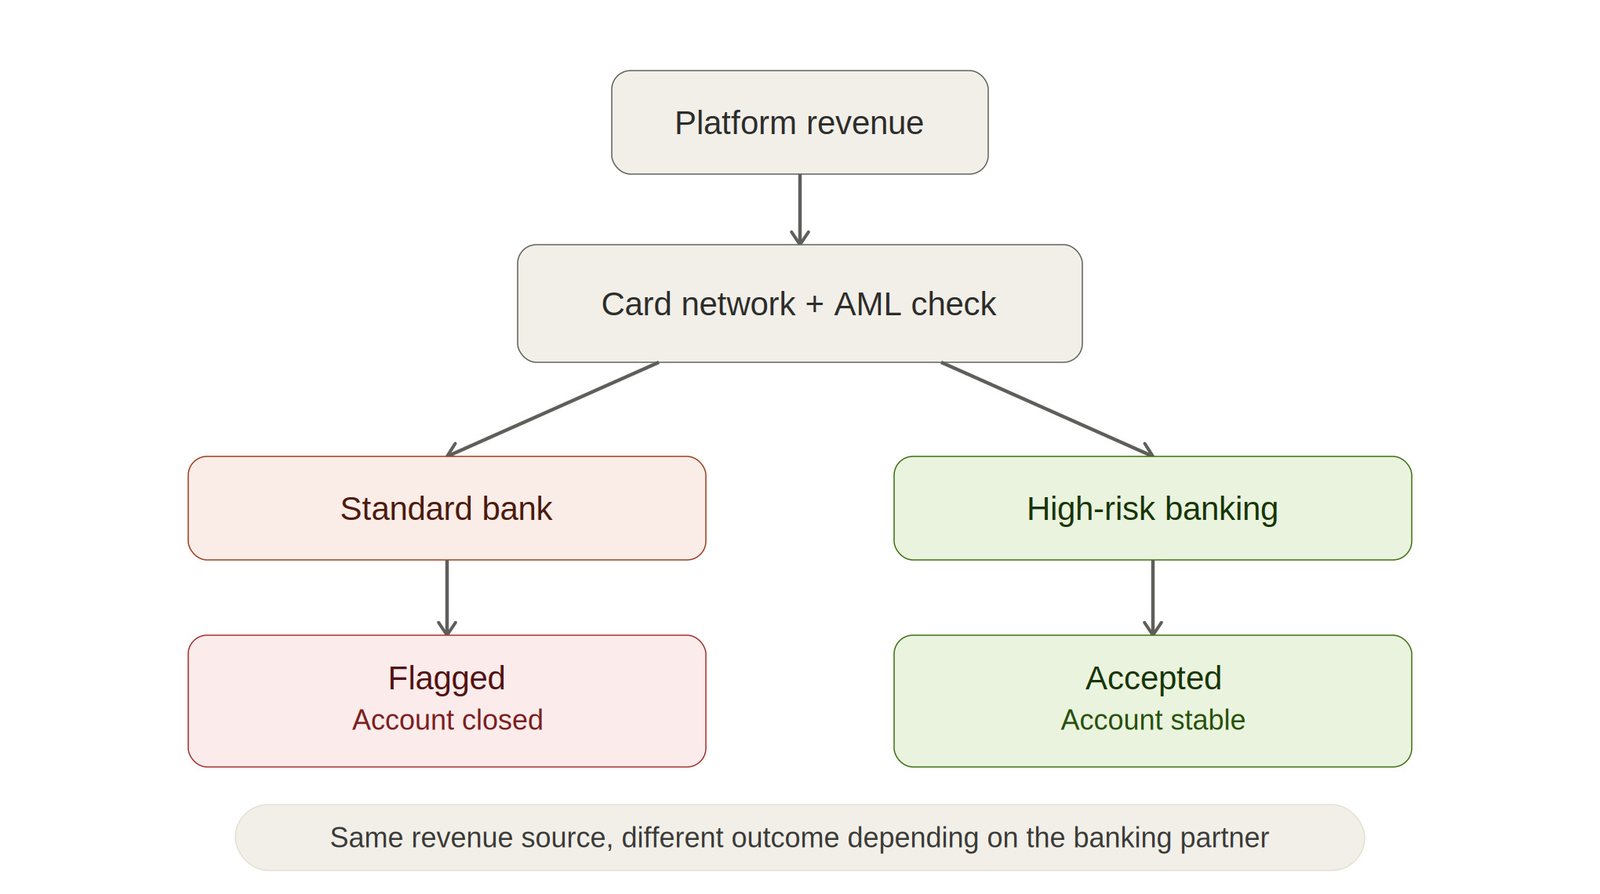
A cleanly registered LLC, solid corporate bookkeeping, a legal contract with every creator, none of that changes what happens the moment a standard commercial bank notices incoming wires or ACH deposits tracing back to adult monetization platforms like OnlyFans, Fansly, or Fanvue. The account can be closed without much warning.
Adult content monetization is broadly classified as a high-risk industry by mainstream financial networks, which means agencies in this space run into a specific set of compliance gates, higher fees, and account closures that other businesses generally don't.
Scaling an agency on a retail banking app or an informal payment workaround isn't a long-term setup. Here's how the high-risk banking landscape actually works, and what a legitimate, durable setup for automated revenue-sharing looks like.
1. Why standard banks decline adult-industry accounts
Mainstream financial institutions operate under rules set by the major card networks and standard anti-money-laundering requirements. A few specific factors push adult-industry accounts into high-risk territory at most banks:
- Chargeback rates. Content platforms see a higher rate of disputed charges than many other industries, often from "friendly fraud," where a legitimate purchase gets disputed later anyway. Banks weigh high chargeback rates as a real financial liability.
- Reputational policy. Many commercial banks have explicit internal policies steering away from adult-content-adjacent business, independent of how that specific business actually operates.
- Third-party payout patterns. A standard bank often has no easy way to verify the relationship between an agency and an individual creator, so incoming revenue routed to a corporate account from an individual's platform earnings can get flagged as a potential third-party exploitation pattern, even when the underlying arrangement is entirely legitimate.
Running agency capital through a personal checking account or a standard neobank account doesn't avoid this, it just delays it. A routine compliance review eventually catches the transaction pattern.
2. What a legitimate high-risk banking setup actually looks like
Handling six or seven figures in annual revenue safely means moving off generic banking apps and onto financial infrastructure built for this category specifically. That generally rests on three things:
Specialized merchant banking and payment providers. Agencies work with merchant banking institutions and payment networks, boutique providers and enterprise-grade digital wallets such as Paxum or CosmoPayment are examples, that explicitly underwrite adult-industry accounts rather than accepting them as an exception to a general policy. These providers build their compliance frameworks around absorbing this kind of transaction volume without triggering the automated flags a mainstream bank would raise.
Dedicated accounts per model, not one pooled account. Rather than routing all creator earnings into a single corporate account, a properly built setup provisions a separate account for each individual creator, in her own name. That isolates capital, so a compliance question on one account doesn't put the agency's entire operational funds at risk.
Real corporate and individual KYC. Any platform claiming to move or split adult-industry revenue without requiring real documentation isn't a shortcut, it's a setup likely to be shut down. A legitimate process requires, from the agency, incorporation documents, tax documentation, and beneficial ownership verification, and from each creator, government-issued ID, proof of tax residency, and a standard KYC identity check.
3. Automating the split on top of that foundation
With a compliant banking foundation in place, the remaining piece is automating revenue collection itself, without manual invoices and without sharing anyone's personal wallet credentials.
The structure that handles this safely executes the split downstream, at the banking layer, after funds have already cleared the platform.
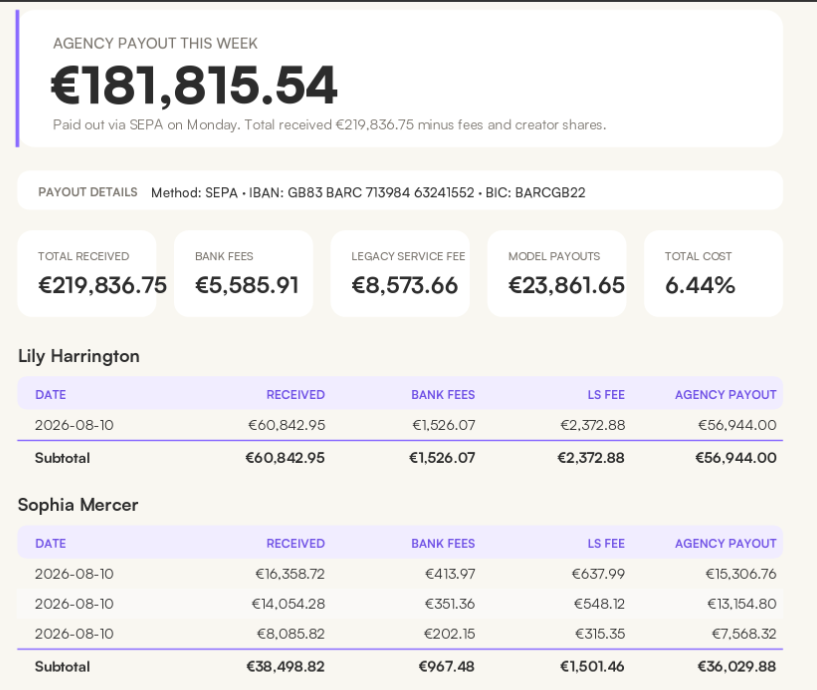
This is how Legacy Solutions is built:
- OnlyFans releases the full weekly cleared earnings to a verified, compliant account created specifically in the model's legal name.
- The moment funds land, a pre-authorized banking directive executes automatically.
- The split calculates based on the agreed contract terms, the agency's percentage routes to its own merchant account, the creator's net share routes separately into hers.
Neither party ever holds the other's login credentials, password, or 2FA. The split happens without altering how OnlyFans itself processes the payout, and no invoice goes out afterward, because both shares were already final the moment the payout landed, not because either side is kept from seeing the numbers.
Frequently asked questions
Why do banks treat adult-industry businesses as high-risk even with clean documentation?
It's largely a categorical policy decision tied to chargeback rates and reputational risk across the industry as a whole, not necessarily a judgment of any individual business's actual compliance or financial health. That's why specialized providers built around this category exist, rather than every adult-industry business eventually qualifying with a mainstream bank.
Is it safe to route agency revenue through a personal checking account in the meantime?
No. It's a common stopgap, but transaction patterns inconsistent with a personal account's stated purpose tend to get caught in a routine compliance review eventually, often resulting in a frozen account with little warning.
Does isolating each creator into her own account actually reduce agency risk?
Yes, meaningfully. If one account draws a compliance question, isolated accounts mean that review doesn't extend to the agency's broader operational funds or every other creator's earnings at the same time.
Does automated splitting replace the need for proper high-risk banking relationships?
No, it depends on one. The automated split executes on top of compliant, dedicated accounts, it doesn't substitute for having genuinely adult-industry-friendly banking infrastructure in place to begin with.